








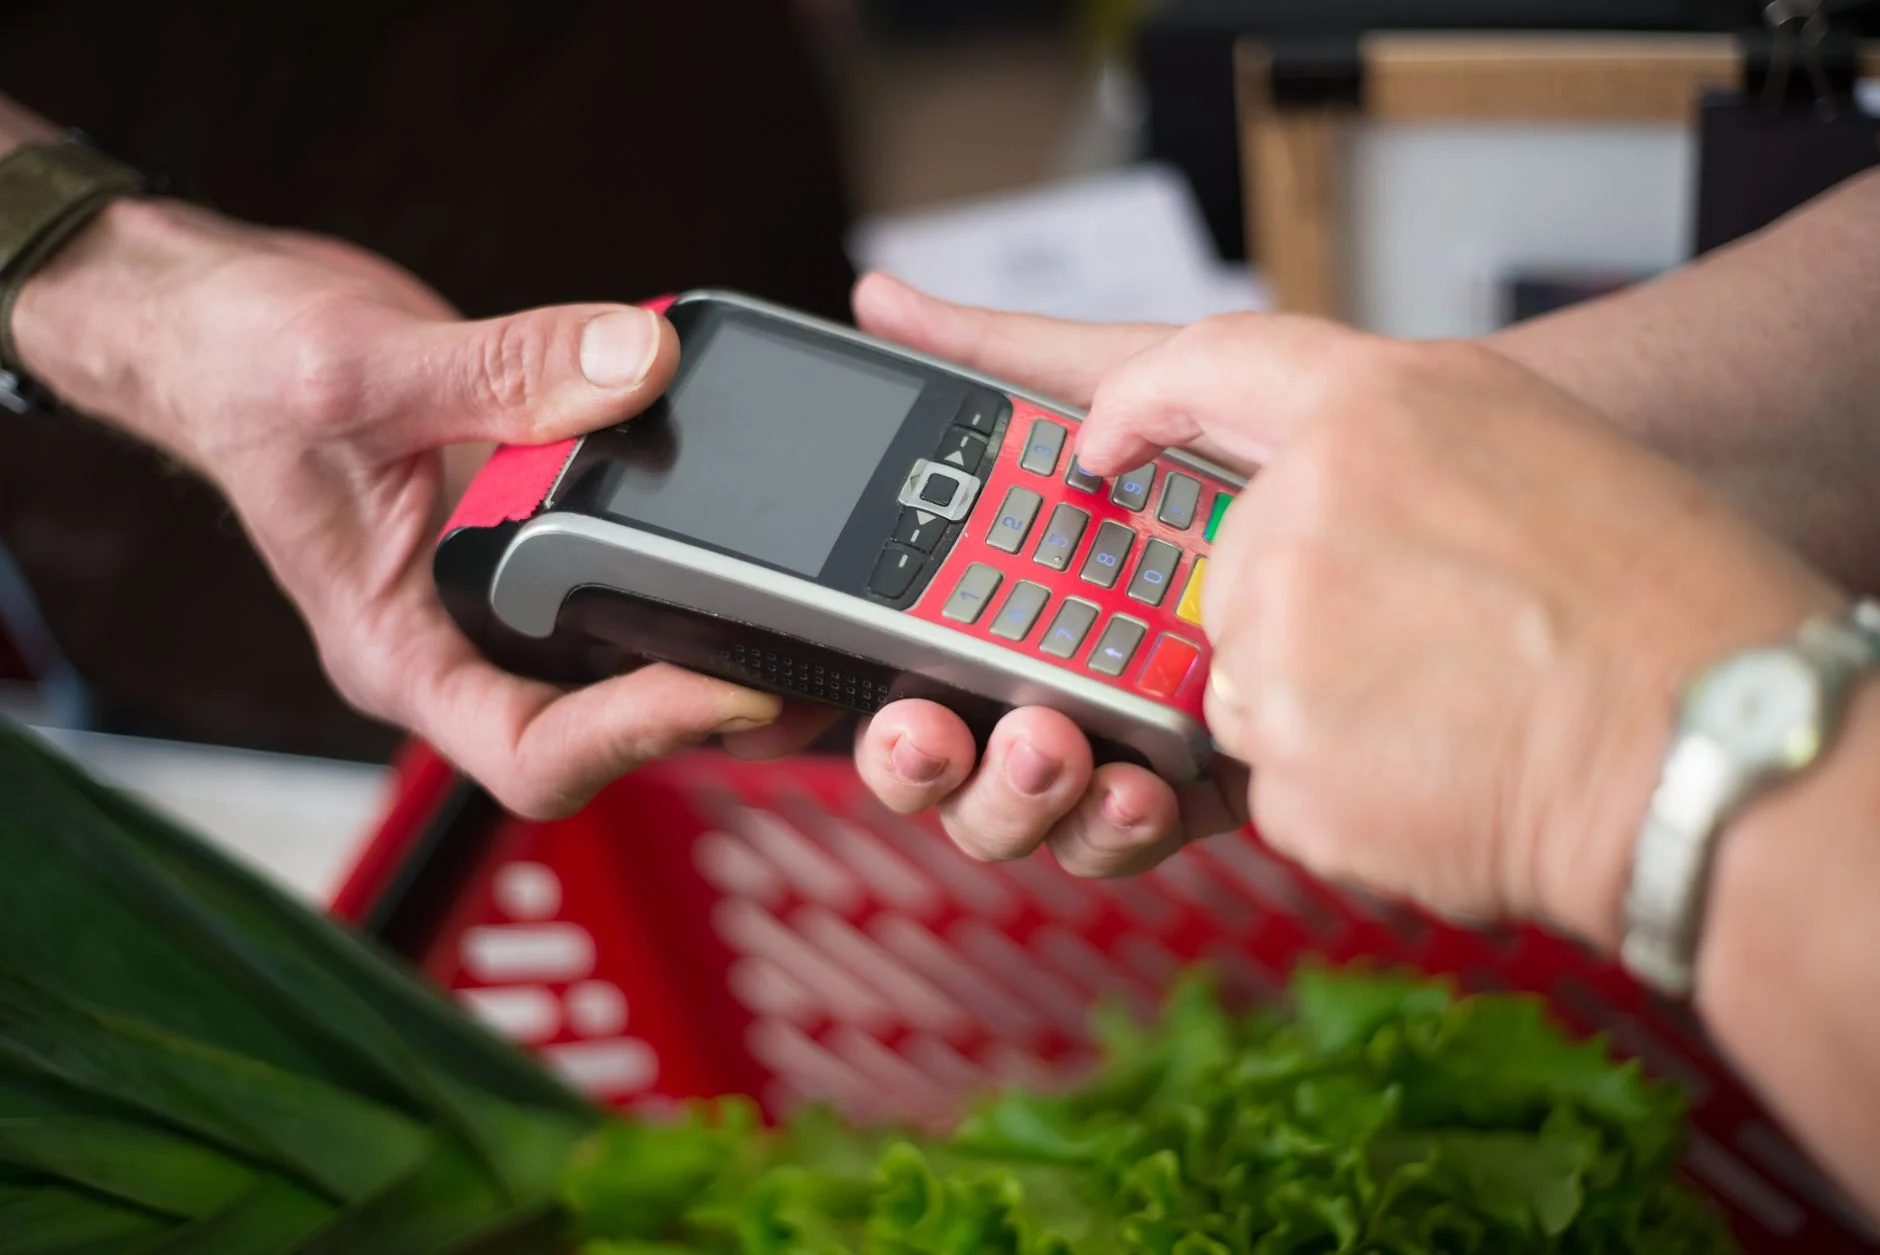
What happened
Over the past decade, emerging markets have witnessed a significant transformation in their financial infrastructure, particularly through the modernization and expansion of payment rails. These underlying systems, which enable the transfer of funds between banks, financial institutions, and consumers, have evolved beyond traditional frameworks to accommodate digital wallets, mobile money, real-time settlement mechanisms, and interoperable platforms. This shift has facilitated greater financial access for populations historically excluded from formal banking systems.
Why it matters
The modernization of payment rails is a critical enabler of financial inclusion, economic development, and social equity. By reducing transaction costs, shortening settlement times, and expanding the reach of financial services, upgraded payment infrastructures empower individuals and businesses in regions where cash remains dominant and banking penetration is low. Improved payment systems not only support everyday transactions but also underpin credit delivery, social welfare distribution, and cross-border remittances, all crucial for sustainable growth in emerging economies.
Industry context
Emerging markets often face unique challenges in financial infrastructure development, including limited legacy systems, fragmented regulatory environments, and uneven technological adoption. Traditional payment rails, designed primarily for high-value, low-frequency transactions, were ill-suited to the needs of these diverse populations. In response, governments, central banks, and private sector players have accelerated efforts to build inclusive and interoperable payment ecosystems. This includes deploying instant payment schemes, fostering mobile money integration, and promoting open banking frameworks to stimulate competition and innovation.
Analysis
The evolution of payment rails in emerging markets reflects a broader paradigm shift toward inclusive digital finance. A key driver has been the rise of mobile money platforms, which leverage widespread mobile phone penetration to bypass conventional banking constraints. These platforms often operate on dedicated rails or integrate with national payment switches, enabling seamless value transfer even in remote areas.
Real-time payment systems have further enhanced these capabilities by enabling instant settlement and confirmation, which reduces counterparty risk and encourages wider adoption among merchants and consumers. Interoperability initiatives have been instrumental in breaking down silos between different payment providers, fostering a more cohesive financial ecosystem. Regulatory support, including mandates for open APIs and standardized protocols, has played a crucial role in harmonizing these developments.
However, challenges persist. Infrastructure disparities, cybersecurity vulnerabilities, and regulatory fragmentation can hinder the scalability and resilience of payment rails. Additionally, ensuring that financial inclusion efforts reach underserved groups—such as women, rural populations, and informal sector workers—requires tailored approaches that address cultural and socioeconomic barriers beyond technological solutions.
What to watch next
Future developments in emerging market payment rails will likely focus on deepening integration with broader financial and digital ecosystems. This includes linking payment systems with credit scoring, microinsurance, and savings products to offer holistic financial services. Advances in distributed ledger technologies and central bank digital currencies could further reshape payment infrastructures by enhancing transparency and cross-border capabilities.
Regulatory frameworks will remain pivotal in balancing innovation with consumer protection and systemic stability. Monitoring how governments and industry stakeholders navigate these trade-offs will provide insights into the sustainability and inclusivity of evolving payment rails. Ultimately, the continued evolution of payment infrastructure will be a bellwether for the broader progress of financial inclusion in emerging markets.
Ask AI about this story
Answers are based on this article and SN Media’s related coverage. AI can make mistakes.
Frequently asked questions
How have payment rails in emerging markets changed over the past decade?
Payment rails have modernized from traditional systems to include digital wallets, mobile money, real-time settlement, and interoperable platforms, enabling greater financial access for previously excluded populations.
What role do mobile money platforms play in the evolution of payment rails?
Mobile money platforms leverage widespread mobile phone use to bypass traditional banking constraints, often operating on dedicated rails or integrating with national payment switches to enable seamless value transfer, even in remote areas.
What challenges remain in expanding payment rail infrastructure in emerging markets?
Challenges include infrastructure disparities, cybersecurity risks, regulatory fragmentation, and the need for tailored approaches to reach underserved groups such as women, rural populations, and informal workers beyond just technological solutions.
What future developments are expected in payment rails for emerging markets?
Future developments may include deeper integration with credit scoring, microinsurance, and savings products, as well as the adoption of distributed ledger technologies and central bank digital currencies, with regulatory frameworks playing a key role in balancing innovation and consumer protection.
Continue the story
 LATEST
How AI Investment is Reshaping Corporate Credit Markets
- LATEST How Private Equity’s Aggressive Talent Hunt is Reshaping Wall Street Careers
- LATEST How Michigan’s Public-Private Partnerships Are Shaping the Future of American Manufacturing
- LATEST The Impact of Raising Bank Asset Thresholds on Financial Stability
- LATEST The Rise of the ‘Spend Now’ Generation: How Pensioners Are Redefining Retirement Finances