








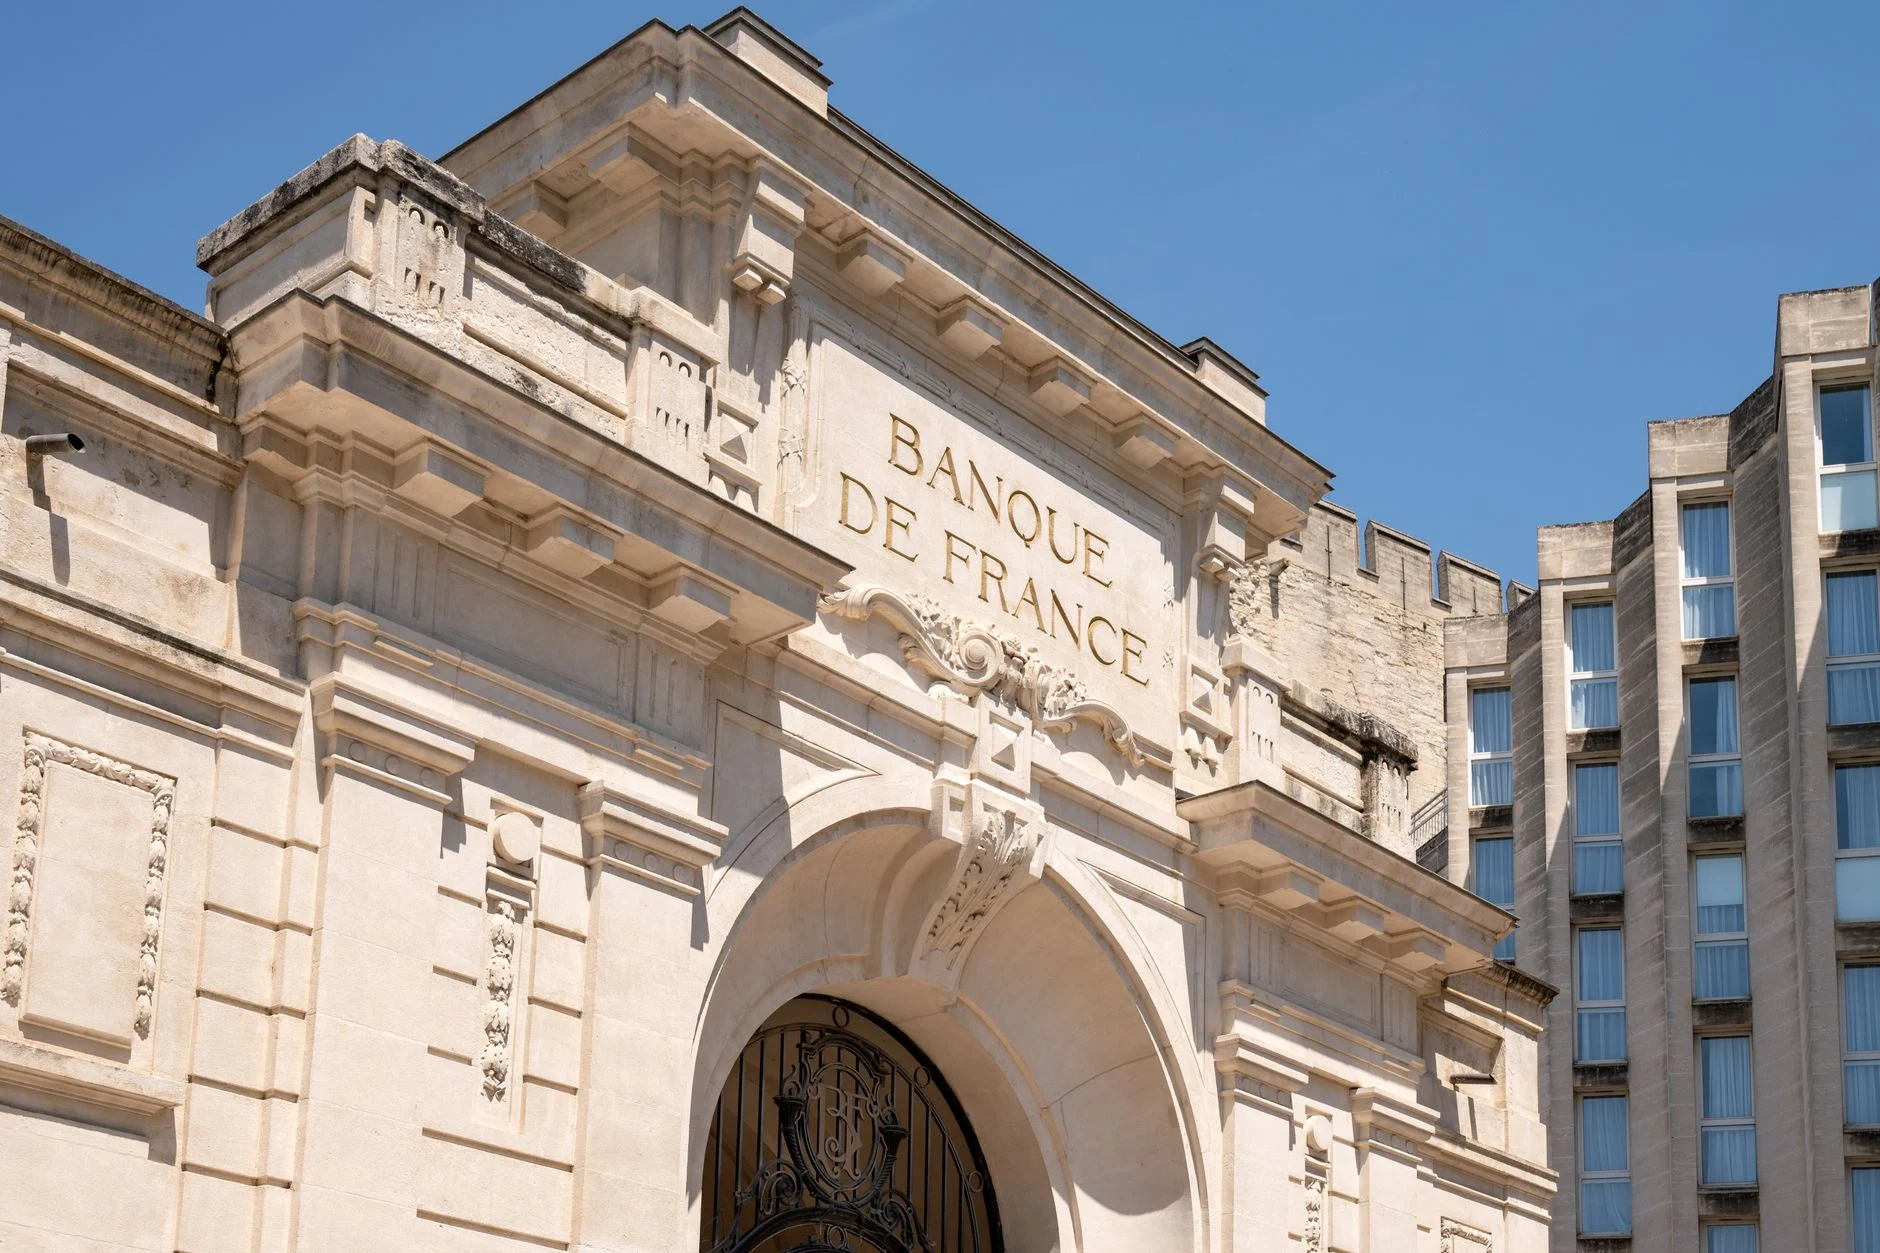
- Collateralized bank bonds in France are currently perceived as less risky than sovereign debt by market participants.
- Underlying credit enhancements and regulatory frameworks underpin the relative safety of these bank-issued securities.
- Contemporary shifts in fiscal policy and sovereign credit outlook have contributed to a recalibration of risk premia.
- Market pricing reflects evolving investor confidence in the French banking sector’s resilience amid macroeconomic uncertainties.
What happened
In recent weeks, a notable inversion has emerged in French credit markets: collateralized bank bonds are trading with tighter spreads and lower risk premiums than traditional French government debt. This phenomenon, unusual in the typical hierarchy where sovereign debt is considered the benchmark for safety, signals a reassessment by investors who now view certain bank-issued securities as comparatively more secure. The trend is evidenced by Bloomberg’s analysis of credit spreads, showcasing a “crazy French inversion” where bonds backed by bank collateral outperform sovereign bonds in risk perception metrics.
Why it matters
The inversion challenges conventional market wisdom that sovereign debt, especially from a developed economy like France, constitutes the safest fixed income asset. It underscores a nuanced shift in investor sentiment that has implications for capital allocation, risk management, and regulatory oversight. If market participants increasingly favor collateralized bank bonds, it may alter funding dynamics for financial institutions and influence sovereign borrowing costs. Moreover, it raises questions about the evolving credibility of government fiscal policies and the robustness of banking sector safeguards amid broader economic uncertainties.
Industry context
Traditionally, government bonds serve as the baseline for credit risk, underpinned by tax authority sovereignty and monetary policy control. Banks, by contrast, typically issue unsecured or secured debt that carries greater default risk. However, collateralized bank bonds benefit from structured credit enhancements—such as asset pledges, overcollateralization, and regulatory protections—which mitigate loss severity. Since the post-2008 financial reforms, European banks have been subject to stricter capital and liquidity requirements, strengthening their balance sheets and reducing systemic risk perceptions. At the same time, France’s sovereign debt faces pressures from protracted fiscal deficits, growing public debt ratios, and political uncertainties influencing market confidence.
Analysis
This inversion reveals complex interplay between credit fundamentals and market psychology. The collateralized bank bonds in question are often backed by high-quality assets and benefit from legal frameworks that prioritize their claims in insolvency scenarios. These features effectively lower expected loss rates compared to sovereign bonds, which remain vulnerable to macroeconomic shocks and political impasses affecting fiscal sustainability.
Simultaneously, investor concerns about France’s fiscal trajectory—with rising debt-to-GDP ratios and episodic political gridlock—have heightened risk premia on government paper. The European Central Bank’s evolving monetary stance and uncertain EU fiscal policy coordination exacerbate these pressures, making sovereign bonds less attractive relative to well-structured bank debt.
Furthermore, French banks’ improved capitalization and asset quality, reinforced by stringent European banking regulations such as the Capital Requirements Directive IV (CRD IV) and Single Resolution Mechanism (SRM), bolster confidence. This regulatory environment reduces tail risk and enhances recoveries, factors that investors price into collateralized bank bonds but not equivalently into sovereign debt.
The result is a market environment where credit quality assessments transcend traditional hierarchies, emphasizing specific instrument features and regulatory context over issuer type alone.
What to watch next
Market participants will closely monitor the trajectory of French public finances, particularly fiscal consolidation efforts and debt management strategies, which could restore or further erode sovereign credit standing. ECB policy decisions, including bond purchase programs and interest rate adjustments, will also influence relative valuations.
On the banking side, developments in asset quality, collateral valuations, and adherence to regulatory capital requirements will affect the perceived safety of collateralized bonds. Any signs of stress or regulatory changes could reverse the current trend.
Additionally, broader European fiscal and monetary integration initiatives may recalibrate risk perceptions across both sovereign and bank credit markets, potentially reshaping the dynamics observed in France. Observing yield curve movements and credit default swap spreads in these sectors will offer critical insights into evolving investor confidence and risk appetite.
Ask AI about this story
Answers are based on this article and SN Media’s related coverage. AI can make mistakes.
Frequently asked questions
Why are French collateralized bank bonds currently seen as less risky than French government debt?
Collateralized bank bonds benefit from credit enhancements like asset pledges and regulatory protections, which lower expected loss rates. Meanwhile, French sovereign debt faces pressures from fiscal deficits, rising public debt, and political uncertainties, increasing its risk premium.
What regulatory factors support the improved perception of French bank bonds?
European banking regulations such as the Capital Requirements Directive IV and the Single Resolution Mechanism have strengthened French banks' capitalization and asset quality, reducing tail risk and enhancing recovery prospects for collateralized bonds.
How does this inversion of risk perception affect market dynamics?
It challenges the traditional view that sovereign debt is the safest asset, potentially altering capital allocation, risk management, and funding costs for banks and the government. Investors now focus more on specific instrument features and regulatory context than issuer type alone.
What developments could change the current risk perception trend between French bank bonds and government debt?
Changes in French fiscal consolidation efforts, ECB monetary policies, banking asset quality, collateral valuations, and regulatory adherence could influence risk perceptions. Broader European fiscal and monetary integration initiatives may also reshape credit market dynamics in the future.
Continue the story
 LATEST
Assessing the Risk of Contagion in Europe’s Government Bond Markets
- LATEST Gabon’s Debt Transparency Issues Highlight Risks in Emerging Market Bonds
- LATEST Why Bonds Are Emerging as Serious Competitors to Stocks After Decades
- LATEST The Global Shift: Understanding Why High Yields on US Treasury Bonds Are Becoming the Norm
- LATEST How Rising Bond Yields Are Reshaping European Equity Markets