
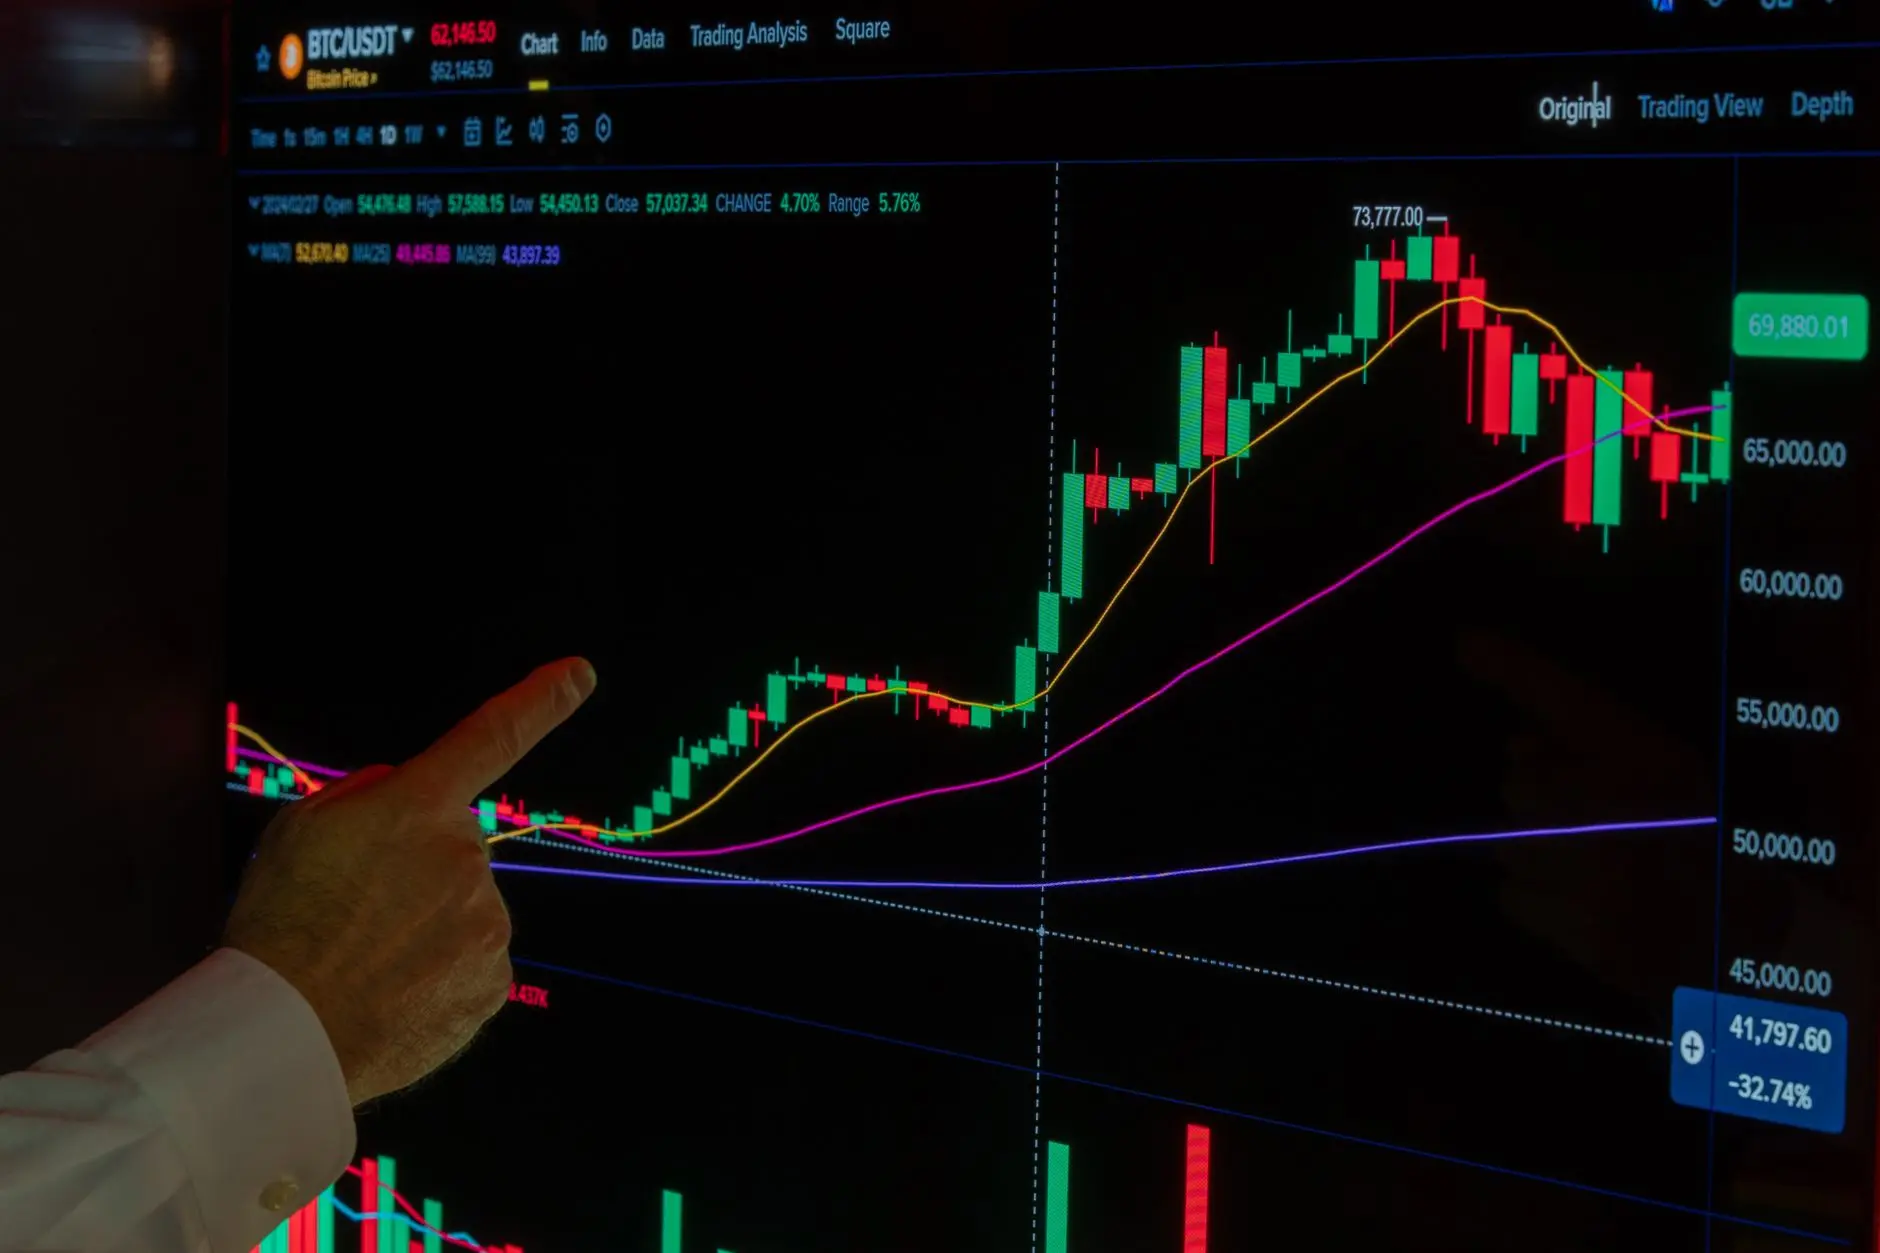
- Markets are underestimating the Federal Reserve’s readiness to extend rate hikes beyond current expectations.
- Bank of America’s Mark Cabana highlights persistent inflationary pressures as a key factor sustaining Fed tightening.
- Investor complacency on rate pause risks mispricing bond yields and equity valuations.
- The Fed’s dual mandate and evolving economic data complicate predictions about the timing of policy normalization.
What happened
Recent market behavior suggests a growing consensus that the Federal Reserve’s cycle of interest rate hikes is nearing its end. Financial markets have priced in a relatively quick transition to a pause or even rate cuts, driven by expectations of slowing inflation and economic deceleration. However, Bank of America’s head of U.S. interest rate strategy, Mark Cabana, has publicly challenged this narrative. In a November 2026 interview, Cabana argued that betting on the conclusion of Fed tightening is premature, emphasizing that the central bank’s policy trajectory remains contingent on ongoing inflation dynamics and labor market conditions.
Why it matters
The misalignment between market expectations and the Fed’s potential policy path carries significant implications for asset allocation and risk management. If investors prematurely price in an end to rate hikes, bond yields may remain elevated for longer than anticipated, compressing returns and increasing volatility. Equities, particularly growth stocks sensitive to discount rates, could face reassessments as borrowing costs stay high. More broadly, the perceived disconnect risks reinforcing market complacency, which can exacerbate corrections when the Fed’s actions diverge from investor assumptions. Understanding the true drivers behind the Fed’s decisions is crucial for navigating the complex post-pandemic economic landscape.
Industry context
Since the inflation surge of 2021-2022, the Federal Reserve has embarked on one of the most aggressive hiking cycles in decades, aiming to rein in price pressures that threatened to become entrenched. While headline inflation has moderated, core inflation metrics remain sticky, and wage growth suggests persistent inflationary forces. The Fed’s dual mandate—maximizing employment and stabilizing prices—means that even as unemployment ticks higher, inflation control remains paramount. Market participants have increasingly debated the timing and pace of policy normalization, with some citing data improvements as signals of an imminent pause. However, the Fed’s communication has consistently underscored data dependence and caution, reflecting uncertainty about the durability of inflation declines.
Analysis
Cabana’s perspective highlights the nuanced interplay between inflation trends, labor market resilience, and monetary policy. Inflation remains elevated in services and shelter costs, sectors less responsive to supply chain improvements. Wage inflation, driven by tight labor markets and worker bargaining power, contributes to a wage-price spiral risk. The Fed’s reluctance to declare victory prematurely stems from the principle that monetary policy operates with lags; decisions today influence economic conditions months ahead. Thus, a premature pause could entrench inflation expectations, risking a costly policy reversal later. Moreover, global economic factors like commodity prices and geopolitical tensions add layers of uncertainty, constraining the Fed’s flexibility. In this context, Cabana’s stance serves as a cautionary reminder that market pricing is not infallible and that monetary policy remains a critical variable requiring close scrutiny.
What to watch next
Investors and analysts should monitor forthcoming inflation reports, especially core CPI and PCE figures, alongside labor market indicators such as wage growth and unemployment claims. Federal Reserve communications, including minutes and speeches from key policymakers, will offer insight into evolving risk assessments and tolerance for inflation deviations. Additionally, the reaction of bond markets to economic data will be telling; a sustained increase in long-term yields could signal skepticism about a near-term Fed pause. International developments, including energy market fluctuations and supply chain disruptions, merit attention as potential inflation catalysts. Ultimately, the trajectory of the Fed’s hiking cycle will hinge on a complex synthesis of domestic data and global conditions, underscoring the need for a measured, data-driven approach to market positioning.
Ask AI about this story
Answers are based on this article and SN Media’s related coverage. AI can make mistakes.
Frequently asked questions
Why does Mark Cabana believe the Federal Reserveu2019s rate hike cycle is not over?
Cabana points to persistent inflationary pressures, especially in services, shelter costs, and wage growth, which suggest that the Fed needs to continue tightening to control inflation and avoid entrenching inflation expectations.
What risks do investors face by assuming the Fed will soon pause or cut rates?
If investors prematurely price in an end to rate hikes, bond yields may stay elevated longer, reducing returns and increasing volatility, while equities sensitive to borrowing costs could be reassessed, potentially leading to market corrections.
How does the Fedu2019s dual mandate affect its interest rate decisions amid current economic conditions?
The Fed must balance maximizing employment with stabilizing prices; even as unemployment rises slightly, controlling persistent inflation remains a priority, complicating predictions about when the Fed will normalize policy.
What indicators should investors watch to gauge the Fedu2019s future policy moves?
Investors should monitor core inflation reports like CPI and PCE, labor market data such as wage growth and unemployment claims, Fed communications including minutes and speeches, bond market reactions, and international factors like energy prices and supply chain issues.
Continue the story
 BACKGROUND · How we got here
Analyzing the Federal Reserve’s Internal Divisions on Interest Rate Policy
- BACKGROUND · How we got here How a Fed Pause Shapes Market Expectations for Year-End Monetary Policy
- BACKGROUND · How we got here How Bank of America’s Macro Traders Navigate Volatile Markets Without Big Bets
- BACKGROUND · How we got here How Wall Street Prepares for Fed Interest Rate Announcements
- BACKGROUND · How we got here Analyzing the Prolonged Risk-Off Sentiment in Global Markets Until Mid-November