








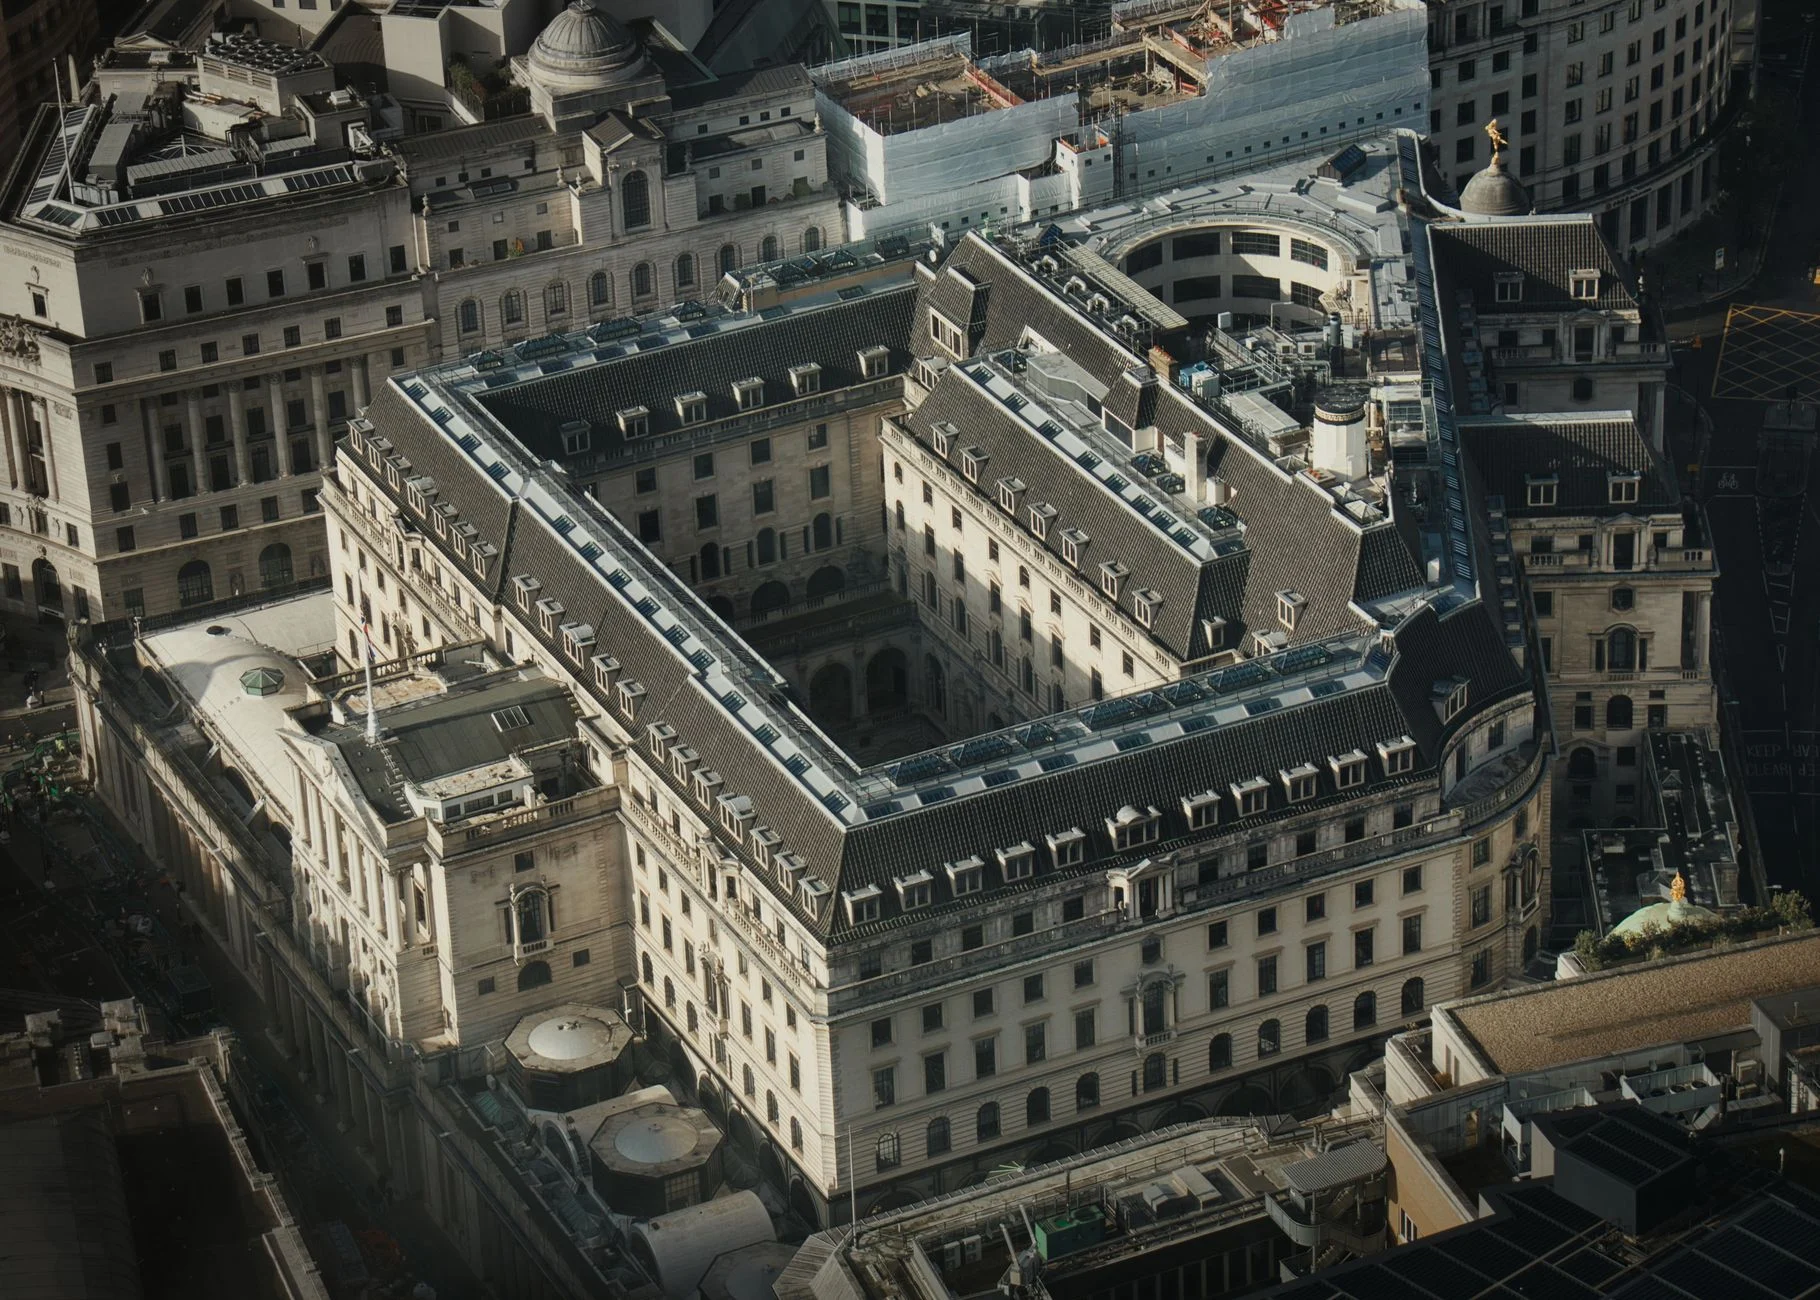
- Bank of England rate adjustments alter mortgage costs, directly affecting housing affordability.
- Rising rates tend to cool buyer demand by increasing monthly repayments and tightening lending criteria.
- Housing supply dynamics interact with rate changes, influencing price trajectories and market liquidity.
- Long-term market stability depends on balancing inflation control with sustainable credit access.
The Ripple Effect: How Bank of England Rate Changes Reshape the UK Housing Market
What happened
The Bank of England (BoE) periodically adjusts its base interest rate to manage inflation and economic growth. Recent rate increases have heightened borrowing costs across the UK, directly impacting mortgage interest rates. This adjustment reverberates through the housing market, reshaping affordability, buyer behavior, and pricing trends. Mortgage rates, tied closely to the BoE base rate, have risen, leading to increased monthly repayments for new and variable-rate borrowers. This shift has prompted a reassessment of housing demand and supply dynamics.
Why it matters
Housing affordability is a cornerstone of economic stability and social well-being. Changes in the BoE’s rate alter the cost of mortgage credit, which dominates household borrowing in the UK. As mortgage repayments rise, prospective buyers face tighter budget constraints, potentially pricing out segments of the market. This can dampen demand, reduce transaction volumes, and exert downward pressure on house prices. Conversely, sellers may become reluctant to list properties amid market uncertainty, tightening supply. The balance between these forces influences not only individual financial health but also broader economic indicators such as consumer spending and wealth distribution.
Industry context
The UK housing market operates within a complex interplay of supply constraints, demographic pressures, and regulatory frameworks. Persistent undersupply of housing stock has historically supported price growth, even during periods of economic stress. However, the market is highly sensitive to credit conditions. Mortgage lending standards, shaped by both regulatory bodies like the Financial Conduct Authority and commercial bank policies, respond to interest rate fluctuations by adjusting loan-to-value ratios and income multiples. Additionally, inflationary pressures and wage growth trends modulate buyers’ capacity to absorb higher borrowing costs. The BoE’s monetary policy thus functions within a delicate ecosystem where its interventions aim to moderate inflation without precipitating a housing market contraction.
Analysis
Rate hikes by the BoE serve as a blunt instrument to curb inflation, but their impact on housing markets is nuanced and multi-layered. Increased mortgage rates directly raise the cost of financing home purchases, reducing the pool of eligible buyers and shifting demand toward more affordable properties or rental markets. This selective pressure can exacerbate regional disparities, favoring areas with lower price points. On the supply side, higher financing costs may delay or deter new construction projects, compounding supply shortages. The resulting market imbalance can lead to increased price volatility.
Lenders, responding to heightened risk and regulatory scrutiny, often tighten lending criteria during periods of rising rates, further constraining access to credit. This credit tightening can disproportionately affect first-time buyers, who are typically more leveraged and sensitive to rate changes. The interplay between monetary policy and credit availability therefore shapes the market’s resilience or vulnerability.
Moreover, the psychological effect on market participants should not be underestimated. Expectations of continued rate rises may lead to preemptive buying or selling, amplifying market swings. The impact on consumer confidence and household financial planning also feeds back into demand patterns, influencing the velocity of transactions.
What to watch next
Monitoring forthcoming BoE decisions and economic indicators will be critical to anticipating further market shifts. Key variables include inflation trends, wage growth, and employment data, which collectively inform the central bank’s rate trajectory. Additionally, developments in mortgage lending policies and regulatory adjustments may alter credit access independently of interest rates.
The interplay between government housing initiatives—such as schemes aimed at increasing supply or supporting first-time buyers—and monetary policy will also shape market outcomes. Observing regional variations in price movements and transaction volumes can provide early signals of emerging imbalances.
Ultimately, the UK housing market’s response to BoE rate changes will reflect an ongoing negotiation between economic stabilization goals and the practical realities of financing the nation’s homes. Understanding these dynamics will remain essential for stakeholders across policy, finance, and real estate sectors.
Ask AI about this story
Answers are based on this article and SN Media’s related coverage. AI can make mistakes.
Frequently asked questions
How do Bank of England rate increases affect mortgage affordability in the UK?
Rate increases raise mortgage interest rates, leading to higher monthly repayments for borrowers, which tightens budget constraints and can price out some prospective buyers.
What impact do rising interest rates have on housing supply and demand?
Higher rates tend to reduce buyer demand by increasing borrowing costs and tightening lending criteria, while sellers may hesitate to list properties, resulting in tighter supply and potential price volatility.
Why are first-time buyers particularly affected by changes in Bank of England rates?
First-time buyers are generally more leveraged and sensitive to rate changes, so tighter lending criteria and increased mortgage costs disproportionately constrain their access to credit.
What factors should be monitored to anticipate future changes in the UK housing market related to BoE rate decisions?
Key factors include inflation trends, wage growth, employment data, mortgage lending policies, regulatory adjustments, government housing initiatives, and regional variations in prices and transaction volumes.
Continue the story
 LATEST
How Rising US Mortgage Rates Are Reshaping the Housing Market Landscape
- LATEST Market Sentiment Darkens: Why Traders Are Increasing Pound Put Options Ahead of UK Budget
- LATEST Analyzing the Federal Reserve’s Latest Rate Hike: Implications for Global Markets
- LATEST How Rising Energy Bills Impact Household Budgets Across the UK
- LATEST How Bond Markets Signal the Federal Reserve’s Next Move